Inheritance tax is one of those subjects that many people prefer not to think about, until a family bereavement forces them to deal with it at the worst possible time. It is also a subject surrounded by myths, half-remembered rules and confident advice from people who have never actually handled an estate. The truth is simpler than the rumours suggest, even though the details can become complicated quickly when property, business assets or gifts are involved.
This guide explains inheritance tax in plain English: what it is, when it can apply, the main kinds of relief and exemption in general terms, the misconceptions that cause the most confusion, and why professional advice is so often worth paying for. It is general information only and is not tax advice. Thresholds, rates and allowances are set by the government and change over time, so always check the current figures and take advice on your own situation before making decisions.
What Is Inheritance Tax?
Inheritance tax is a tax that can be charged on the estate of someone who has died. An estate is, in simple terms, everything the person owned at death, minus what they owed. That usually includes property, savings, investments, personal possessions and any share of jointly owned assets, less debts such as a mortgage or unpaid bills. The tax is generally paid out of the estate itself before what remains is distributed to the people named in the will, or, where there is no will, to the people entitled under the rules that apply when someone dies without one.
It is important to understand that inheritance tax does not apply to every estate. Many estates fall below the relevant threshold and pay nothing at all. Others benefit from reliefs and exemptions that reduce the value on which tax is charged, or remove certain assets from the charge altogether. Whether any tax is due, and how much, depends on the size and composition of the estate, the gifts the person made during their lifetime, and the reliefs that apply to their particular circumstances. For background on how personal tax filing works more generally, see our guide to the self assessment tax return, which explains the separate system for reporting income during a lifetime.
When Does Inheritance Tax Apply?
The most common trigger is death itself. When someone dies, the people handling the estate, usually called executors where there is a will, or administrators where there is not, must work out the value of the estate, check whether any tax is due, and deal with the formal process that allows them to administer it. This is not a step that can be skipped or rushed. Valuations need to be realistic, debts need to be identified, and any lifetime gifts that could still count need to be considered.
Inheritance tax can also be connected to gifts made during a lifetime. The general principle is that gifts are not simply invisible for tax purposes. Some gifts are covered by exemptions and fall outside the charge. Others may still count towards the estate if the person dies within a period after making the gift, with the treatment depending on the type of gift, its value, and the timing. This is why keeping a record of significant gifts, including when they were made and to whom, is so useful for the people who will later administer an estate.
Business owners face an extra layer of questions. Shares in a company, a share of a partnership, or assets used in a trade can form a substantial part of an estate, and their value may not be obvious from a bank balance. Where an estate includes shares in a limited company, our guide to corporation tax gives useful background on how companies are taxed during their lifetime, which is a separate question from what happens to those shares on death. Anyone thinking about the future of a business should also weigh up the alternative of selling it during their lifetime, which is covered in general terms by our business for sale material.
How an Estate Is Valued and Administered
Valuing an estate is often more work than people expect. Property needs a realistic market valuation, not a guess or an old purchase price. Investments need to be valued at the relevant date. Personal possessions of significant value, such as vehicles, jewellery or collections, may need professional valuation too. Jointly owned assets can be particularly tricky, because the share that belongs to the estate depends on how the asset was owned, and that is not always the same as an equal split.
Once the value is established, the executors or administrators work out whether the estate is above the threshold, apply any reliefs and exemptions, and calculate whether tax is due. If tax is due, it is normally paid from estate funds, and there are arrangements for situations where the estate is largely made up of property or other assets that cannot be sold immediately. The administration process itself, including obtaining the legal authority to deal with the estate, cannot be completed until the tax position has been properly addressed, which is one reason early advice and good paperwork matter so much.
Record-keeping is the unglamorous part of estate planning, and it is also the part that saves families the most stress. A will that is easy to find, a list of accounts and policies, details of property ownership, and a record of significant gifts all make the job of the executors far easier. Without them, even a straightforward estate can turn into a long search through paperwork at a time when the family is grieving.
Main Reliefs and Exemptions in General Terms
Reliefs and exemptions are the reason so many estates pay less tax than a headline description might suggest, or pay none at all. They are also the area where general guidance must stop and personal advice must begin, because eligibility depends on exact circumstances. The following are the main kinds of relief and exemption in broad terms only, and the current rules, limits and conditions should always be checked before relying on any of them.
- Gifts between spouses and civil partners. In general, transfers between spouses and civil partners during a lifetime, and on death, are treated favourably, and unused allowances can in some circumstances be transferred between them. The precise conditions matter, so this should be confirmed for each couple.
- Gifts to charities. Gifts to qualifying charities are generally exempt, and charitable giving from an estate can in some circumstances affect the overall tax position. This is one reason charitable bequests are a common feature of wills.
- Regular annual gifting. There is a general concept of an annual exemption for gifts, allowing a certain amount to be given each year without it counting for inheritance tax purposes, with unused amounts sometimes carried forward for a limited time. The current amount and the carry-forward rules should be checked, as they change.
- Small gifts and regular gifts from income. Small gifts to individuals, and regular gifts made out of surplus income that leave the giver with enough to maintain their normal standard of living, are treated under separate exemptions in general terms. Both depend on careful record-keeping and on the pattern of giving being genuinely regular.
- Business and agricultural relief. Certain business assets and agricultural property can qualify for relief that reduces their taxable value, sometimes substantially. These reliefs have detailed qualifying conditions about the nature of the business or land, how long it has been owned, and how it is used, and they are among the most commonly misunderstood areas of the whole subject.
- Relief for the family home in some circumstances. There are additional provisions connected with passing on a home to direct descendants in certain situations, subject to conditions and limits. Whether they apply depends on the value of the estate and the family circumstances, and they should never be assumed.
The key point about every item on that list is the same: none of them is automatic in every case. Reliefs have conditions, time requirements and exclusions, and claiming a relief incorrectly can create problems later. A professional adviser can check which reliefs genuinely apply, what evidence is needed, and how they interact with each other, which is rarely obvious from a general guide.
Common Misconceptions
One of the most persistent misconceptions is that inheritance tax applies to everything a person leaves, regardless of size. In reality, the threshold means that many estates are not liable at all, and reliefs and exemptions further reduce the number that pay the full headline charge. Another common belief is that giving everything away shortly before death removes the problem entirely. Lifetime gifts are subject to their own rules, and gifts made close to death can still be brought into account, so last-minute transfers are not a reliable plan and can create disputes within a family.
A third misconception is that a will alone solves inheritance tax. A will is essential, because it decides who receives what and who administers the estate, but a will does not by itself remove a tax charge. Tax planning is about the structure of ownership, the timing of gifts, the use of reliefs, and the interaction with other taxes, all of which need to be considered alongside the will rather than assumed to follow from it.
Business owners sometimes assume that business assets are always exempt, or always fully taxable. Neither is true. Some business assets qualify for relief and some do not, and the distinction often turns on details such as whether the business is genuinely trading, how assets are used, and how long they have been held. Similarly, people sometimes assume that jointly owned property automatically passes outside the estate. In some forms of joint ownership that is broadly true, but in others the deceased person’s share does form part of the estate, and the form of ownership should be checked rather than guessed.
Finally, there is the belief that inheritance tax is only a concern for the very wealthy. Rising property values mean that estates which would once have been comfortably below the threshold can now be much closer to it, especially where a family home forms most of the value. That does not mean every homeowner will face a bill, but it does mean that dismissing the subject without checking is unwise, particularly for couples whose combined estates, property and savings should be considered together.
Why Professional Advice Matters
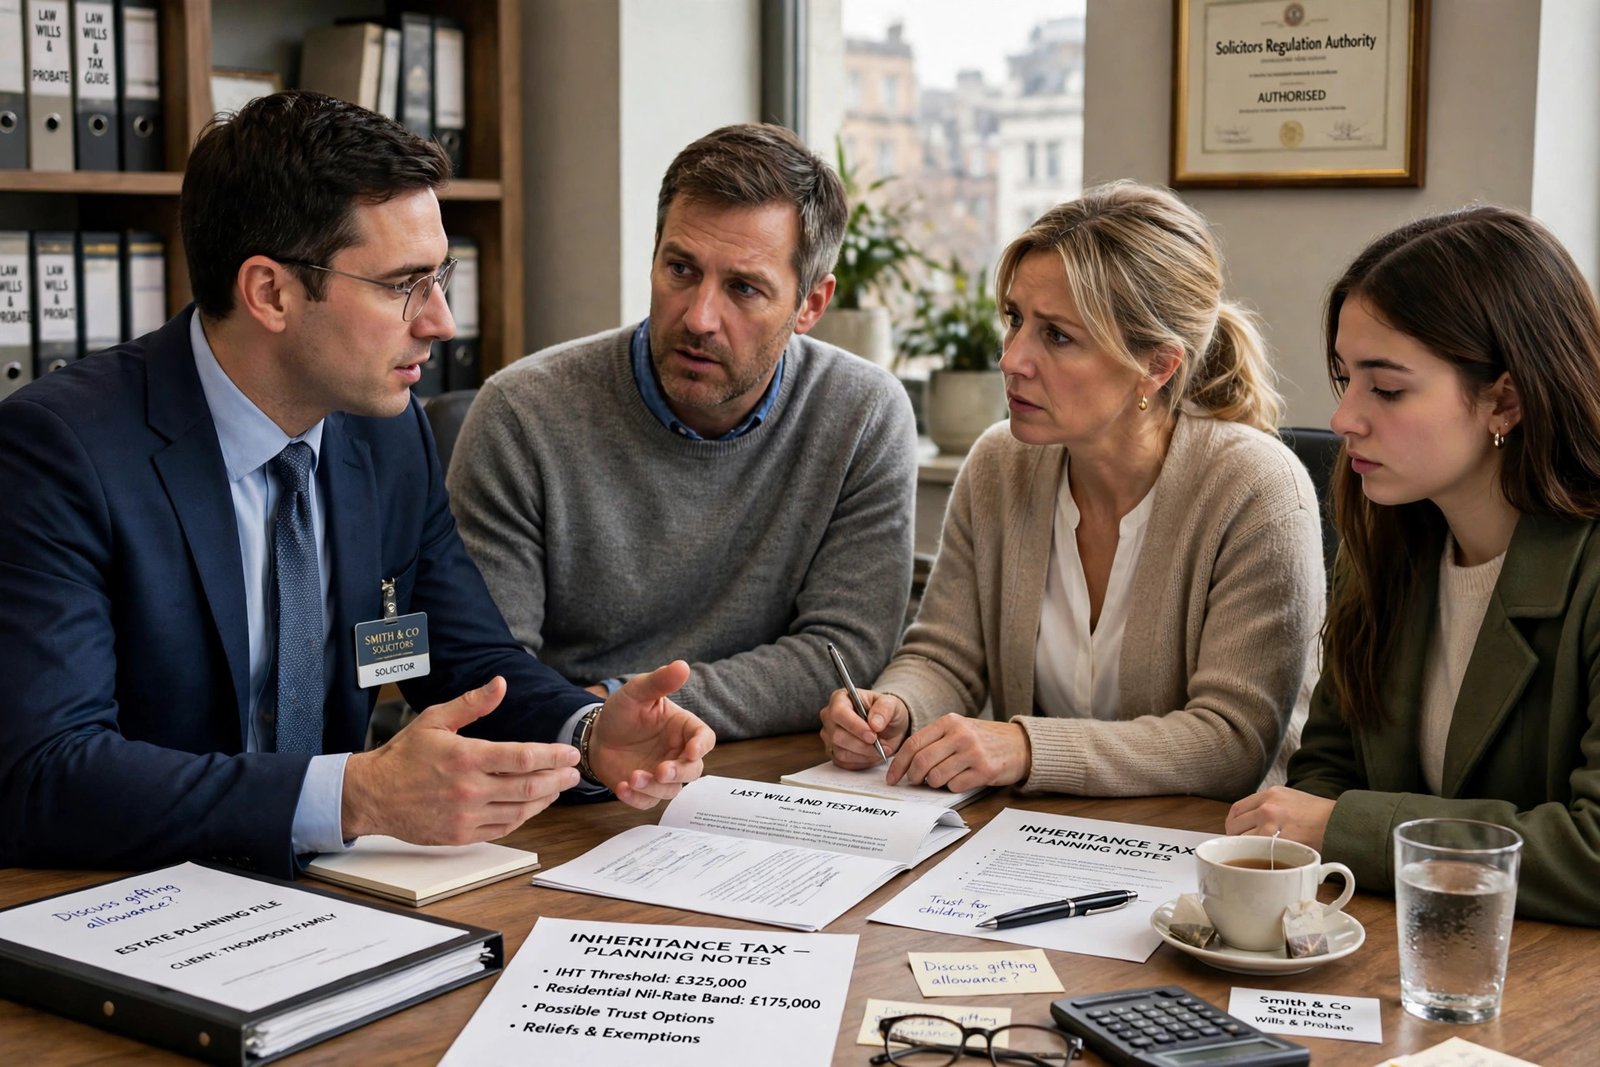
Inheritance tax sits at the meeting point of tax law, property law, family circumstances and business ownership, and that combination is exactly where general information reaches its limits. A solicitor or tax adviser can review a will, check the ownership of property and business assets, look at the history of gifts, and identify reliefs that apply, as well as risks that a general guide cannot foresee. They can also help families avoid the two most common and costly errors: doing nothing until it is too late, and acting on a misunderstood rule that makes the position worse.
Advice is particularly important where the estate includes a business, agricultural land, property abroad, a trust, or a complex family situation such as children from more than one relationship. It is also important where a person wants to make substantial gifts, set up a trust, or change the ownership of property, because those steps can have inheritance tax consequences as well as consequences for other taxes and for control of the assets. The cost of advice should be weighed against the size of the estate and the tax that might otherwise be paid unnecessarily, or the dispute that might otherwise arise among beneficiaries.
Timing matters too. Planning made years in advance, with proper records, is almost always more effective and less stressful than planning attempted in a hurry. Regular reviews are sensible as well, because family circumstances change, property values move, and the tax rules themselves are revised. A plan that was sound a decade ago may no longer fit, and a will that has not been reviewed may no longer reflect a person’s wishes.
Frequently Asked Questions
Does every estate pay inheritance tax?
No. Many estates fall below the threshold or benefit from exemptions and reliefs and pay nothing. Whether tax is due depends on the total value of the estate, lifetime gifts, and the reliefs that apply in that particular case.
Is a gift made during my lifetime free from inheritance tax?
Not necessarily. Some gifts are covered by exemptions, but others may still count if the giver dies within a period after making the gift. The treatment depends on the type of gift, its value and the timing, so significant gifts should be recorded and discussed with an adviser.
Does having a will remove inheritance tax?
No. A will decides who inherits and who administers the estate, which is essential, but it does not by itself remove a tax charge. Tax planning and the will should be considered together.
Are business assets exempt from inheritance tax?
Some business assets may qualify for relief, but the rules are detailed and depend on the nature of the business, how assets are used, and how long they have been held. Business assets should never be assumed to be exempt without advice.
Should I give assets away to avoid inheritance tax?
Giving assets away can have inheritance tax consequences, as well as effects on other taxes, on control of the assets, and on family relationships. It should only be done after advice that looks at the whole picture, not on the basis of a single rule read in isolation.
Conclusion
Inheritance tax is best understood as a tax on larger estates that is shaped, and often substantially reduced, by thresholds, exemptions and reliefs. Understanding the general principles helps families ask the right questions, keep the right records, and avoid the misconceptions that cause the most trouble. It does not replace personal advice, and it should not be used as the basis for transferring property, making large gifts, or restructuring a business.
The practical steps are straightforward: make or review a will, keep clear records of assets and significant gifts, understand in general terms whether your estate is likely to be near the threshold, and take professional advice while there is still time to act on it. Done calmly and in advance, estate planning is a kindness to the people who will one day have to administer it. This guide is general information only and is not tax advice; thresholds, rates and allowances are set by the government and change over time, so check the current figures and speak to a qualified adviser about your own situation.