Almost every financial decision a household or a business makes is affected by one number, even when that number is never mentioned in the conversation. The cost of a loan, the return on savings, the monthly payment on a mortgage, and the price a business pays to expand all move with the interest rate. Yet many people understand interest rates only vaguely, as something that goes up or down in the news, without a clear sense of why it moves or how it reaches their own bank account.
This guide explains interest rates in plain English: what an interest rate is, what moves it, how it affects borrowing, savings and mortgages in general terms, and the difference between fixed and variable rates in concept. It is general information only and is not financial advice. No current rate figures are stated here, because rates change and any figure quoted today could be out of date tomorrow; always check current rates from a lender or adviser before making a decision.
What Is an Interest Rate?
An interest rate is, at its simplest, the price of borrowing money, or the reward for lending it. When you borrow, the lender charges interest as the cost of letting you use their money for a period, and of taking the risk that you might not repay it. When you save, the bank pays you interest as a reward for letting it use your money, which it can then lend to others. In both cases the rate is normally expressed as a proportion of the amount borrowed or saved, applied over a period of time, most commonly a year.
A helpful way to think about it is to imagine renting something. Just as rent is the price of using a property you do not own, interest is the price of using money you do not own. The longer you use it, and the greater the risk to the lender, the more you would expect that price to reflect. That is why different borrowers, different types of loan, and different lengths of borrowing can all carry different rates, even at the same moment in time.
Interest can work in two broad ways. With simple interest, the charge or reward is calculated only on the original amount. With compound interest, interest is also charged or paid on interest already added, so the balance grows more quickly over time. Compounding is one reason that leaving savings untouched for a long period, or leaving a debt unpaid for a long period, can have a much larger effect than people expect from the headline rate alone.
What Moves Interest Rates?
The most influential rate in the UK is the central bank rate set by the Bank of England. Commercial banks and other lenders watch that rate closely, because it affects what it costs them to borrow money themselves, and therefore what they charge their own customers. When the central bank rate rises, borrowing generally becomes more expensive across the economy. When it falls, borrowing generally becomes cheaper. The movement is rarely immediate or identical for every product, but the direction of travel usually filters through.
Inflation is one of the main reasons the central bank moves its rate. Inflation means that prices in general are rising, so money buys less over time. Raising interest rates makes borrowing more expensive and saving more attractive, which tends to cool spending and, over time, ease pressure on prices. Cutting rates has the opposite effect, encouraging borrowing and spending. The central bank therefore balances the desire to support economic activity against the need to keep inflation under control, and that balancing act is a major driver of rate changes.
Other factors matter too. The overall state of the economy, employment, wage growth, global financial conditions, and the level of confidence among lenders and borrowers all influence what rates lenders are willing to offer. Individual risk matters as well. A borrower with a strong credit history, secure income and valuable security to offer will usually be offered a lower rate than a borrower who presents more risk, because the lender expects a greater chance of being repaid in full and on time.
It is worth remembering that there is no single interest rate for the whole economy. There is a central bank rate, there are rates at which banks lend to each other, and there are the many different rates offered to households and businesses for mortgages, loans, overdrafts, credit cards and savings accounts. They tend to move in the same broad direction, but the gaps between them, and the speed at which they move, can vary a great deal.
Borrowing: Loans, Overdrafts and Credit
For individuals, borrowing usually means a personal loan, an overdraft, a credit card, or a mortgage, each with its own structure and its own way of charging interest. A personal loan typically has a fixed repayment schedule, so the borrower knows the monthly payment in advance. An overdraft is more flexible, allowing a current account to go below zero up to an agreed limit, but it can be expensive if used for a long period. Credit cards offer flexibility too, but the rate applied to a balance left unpaid can be high, which is why clearing a card balance in full each month is so often recommended.
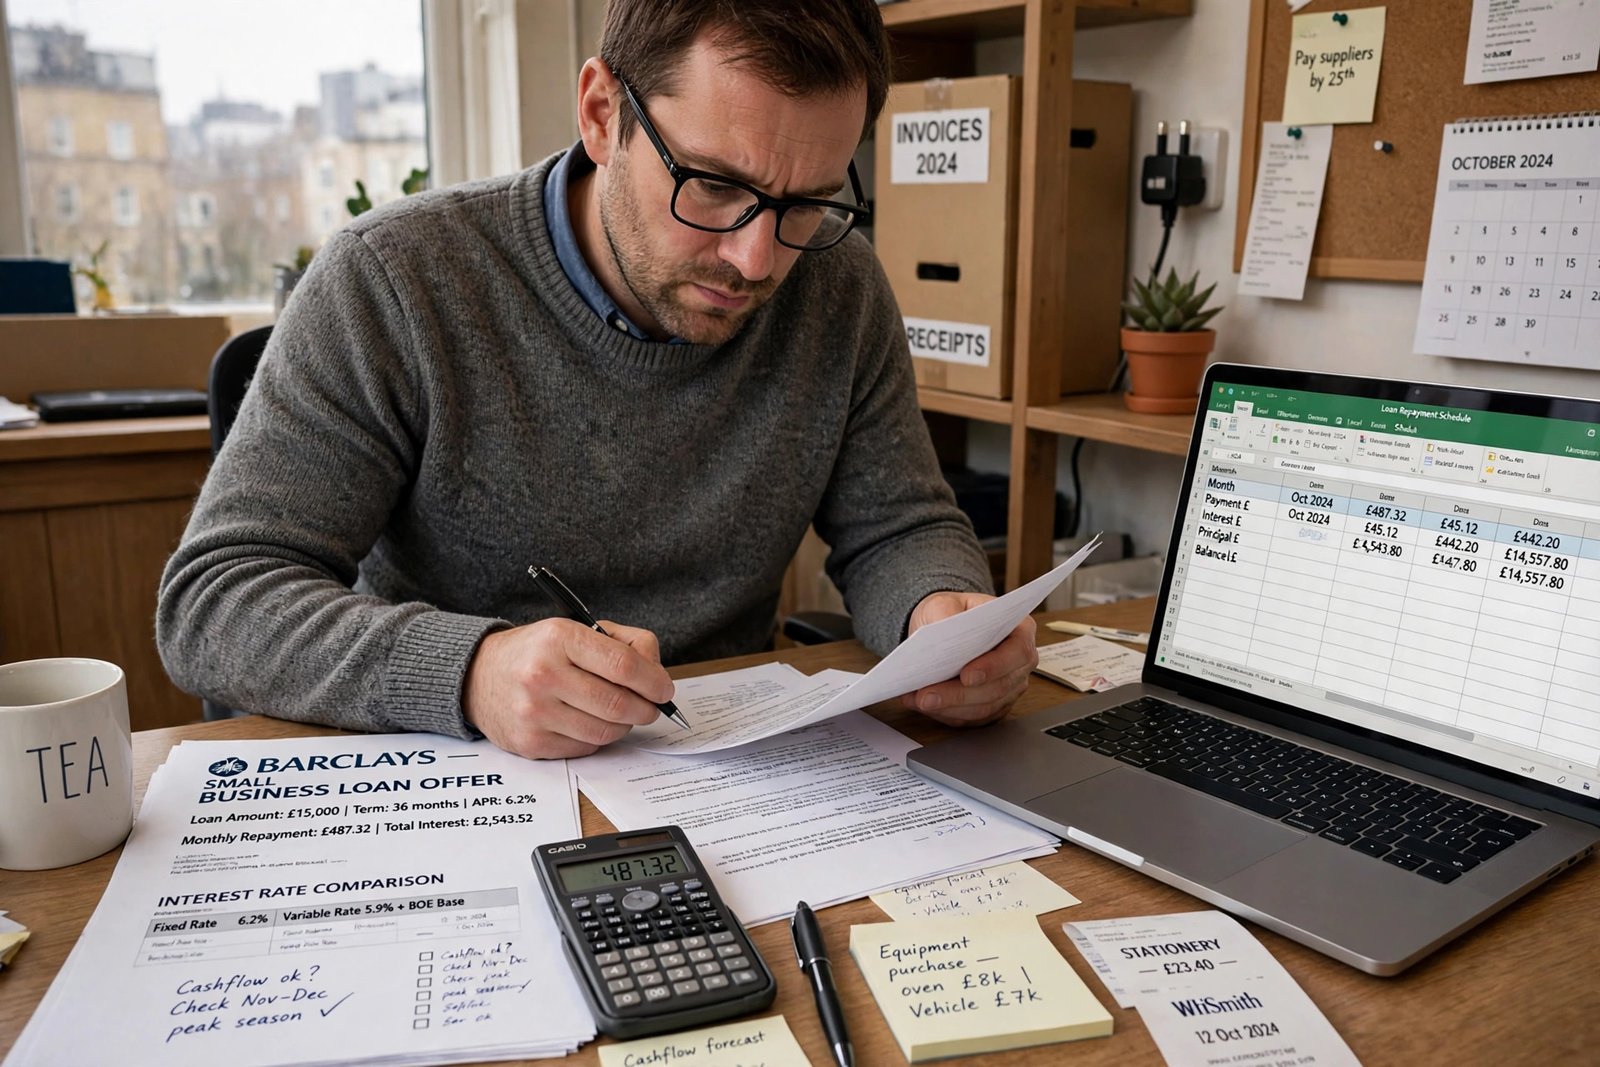
For businesses, borrowing serves a wider range of purposes: buying equipment, funding stock, bridging the gap between paying suppliers and being paid by customers, or financing expansion. A term loan provides a lump sum repaid over an agreed period, while an overdraft provides short-term flexibility for cash flow. Other forms of business finance, such as invoice finance or asset finance, charge for the service in different ways, but the underlying principle is the same: the business pays for the use of someone else’s money, and the cost depends on the amount, the duration and the risk.
When rates rise, the cost of all of this borrowing rises too, although not always at once. Borrowers on variable rates feel the change quickly, while borrowers on fixed rates are insulated until their fixed period ends. Businesses that rely heavily on borrowing therefore need to think about how a rise in rates would affect their monthly costs, their profit margins, and their ability to invest. A business considering borrowing to buy an existing business, for example, should weigh the cost of finance alongside the price and prospects of the business itself, as discussed in our business for sale material.
Savings: Why Rates Matter to Savers
Interest rates cut both ways. While borrowers dislike rising rates, savers generally welcome them, because a higher rate means a better return on money held in savings accounts. That return is not, however, the whole story. If inflation is running higher than the rate paid on savings, the purchasing power of those savings is still falling, even though the balance is growing. Savers therefore need to think in terms of the return after inflation, not just the headline rate.
Different savings products pay interest in different ways. An easy-access account allows money to be withdrawn at any time, but usually pays a lower rate in return for that flexibility. A fixed-term account or notice account typically pays a higher rate, but the money is locked away for a period or can only be withdrawn after giving notice. Cash ISAs and other tax-advantaged accounts add another consideration, because the tax treatment of the interest can matter as much as the rate itself.
Savings interest can also have tax implications. Interest earned on savings may need to be considered as part of a person’s overall tax position, depending on their total income and the allowances that apply. Readers who need to report income of this kind may find our guide to the self assessment tax return useful background, although the tax treatment of savings should always be checked for the current tax year.
Mortgages in General Terms
A mortgage is usually the largest borrowing most people ever take on, so interest rates have a bigger effect here than anywhere else in household finance. The monthly payment on a mortgage is made up of interest on the amount borrowed, plus repayment of the amount itself, and the balance between those two parts changes over the life of the loan. Early on, a larger share of each payment goes on interest. As the balance falls, more of each payment reduces the amount owed.
Because mortgages run for many years, even a modest change in the rate can make a noticeable difference to the monthly payment and to the total amount repaid over the full term. That is why mortgage borrowers pay close attention to rate changes, and why the choice between fixed and variable rates, discussed below, feels so consequential. It is also why lenders assess affordability carefully, looking at income, existing commitments and a margin for rate rises, before agreeing to lend.
Businesses can face similar questions when borrowing secured against commercial property, although the products, terms and assessment criteria differ from residential mortgages. In both cases, the same principle applies: the longer the borrowing lasts, and the larger the amount, the more sensitive the borrower is to movements in the rate.
Fixed Versus Variable in Concept
The distinction between fixed and variable rates is one of the most important concepts in borrowing, and it applies to mortgages, loans and some business finance alike. With a fixed rate, the interest rate is set for an agreed period, and the payment stays the same during that period regardless of what happens to rates in the wider economy. With a variable rate, the rate can move up or down during the borrowing, usually following changes in the lender’s own rate or in the central bank rate, and the payment moves with it.
Fixed rates offer certainty. A household or business that fixes its rate knows exactly what it will pay each month for the fixed period, which makes budgeting far easier. The trade-off is that if rates in general fall during the fixed period, the borrower does not benefit, and leaving a fixed deal early can involve charges. Variable rates offer flexibility and the chance to benefit if rates fall, but they carry the risk that payments will rise, sometimes sharply, if rates move upwards.
Neither choice is right in every situation. The decision depends on how much certainty the borrower needs, how much room there is in the budget for a rise in payments, how long the borrowing will last, and what the borrower expects to happen to rates, while accepting that no one can predict rate movements with certainty. Many borrowers split the difference in practice, fixing part of a borrowing and leaving part variable, or fixing for a shorter period to preserve flexibility.
How Businesses Plan Around Interest Costs
For a business, interest is a cost like any other, and it needs to be planned for rather than discovered. A business that borrows should model what its repayments would look like if rates rose, not just at the current rate, and should keep a cash buffer for periods when sales are slow or costs rise unexpectedly. Businesses with variable-rate borrowing are more exposed to rate rises, while businesses that have fixed their rates have more certainty but may face a step change in costs when the fixed period ends.
Interest costs also interact with tax and with investment decisions. For a limited company, the way borrowing costs are treated for tax purposes, and the way profits are taxed overall, can affect whether borrowing to invest makes commercial sense. Our guide to corporation tax gives background on how limited companies are taxed, which is part of that wider calculation. The decision to borrow should always be based on the expected return from the investment, the certainty of the cash flows that will repay it, and the risk if those cash flows disappoint, not on the availability of credit alone.
Good financial discipline helps in any rate environment. That means borrowing for a clear purpose, understanding the total cost over the full term rather than just the monthly payment, reading the terms for charges on early repayment or missed payments, and reviewing borrowing regularly as rates and business conditions change. Refinancing, switching products, or repaying borrowing early can all make sense in some circumstances, but each step should be weighed against its costs and against the business’s wider plans.
Common Misconceptions
One common misconception is that the central bank rate is the rate everyone pays. In reality, it is a benchmark that influences other rates, but the rate any individual or business actually pays depends on the product, the lender, the term, and the borrower’s risk profile. Two borrowers approaching different lenders on the same day can be offered quite different rates.
Another misconception is that a low rate means borrowing is cheap in every sense. The headline rate is only part of the cost. Fees, charges, the length of the borrowing, and whether the rate is fixed or variable all affect the total amount repaid. Comparing the total cost over the full term, not just the advertised rate, gives a truer picture.
A third misconception affects savers: that any positive rate means savings are growing in real terms. If prices are rising faster than the rate paid, savings are losing purchasing power even as the balance rises. Savers should therefore look at the rate in the context of inflation, and at whether a different product, or a different use of the money, might serve their goals better, taking advice where the sums are significant.
Finally, many people assume that interest rates only matter to borrowers and savers directly. In fact, rates affect the whole economy: business investment, employment, house prices, exchange rates and pension returns are all influenced by the cost of money. That is why rate decisions attract so much attention, and why understanding the basic mechanism is useful even for people who neither borrow nor save a great deal at the moment.
Frequently Asked Questions
What is the difference between a fixed and a variable interest rate?
A fixed rate stays the same for an agreed period, so payments are predictable during that period. A variable rate can move up or down, so payments can rise or fall with changes in the lender’s rate or the central bank rate.
Why do interest rates rise and fall?
Rates move mainly in response to inflation, the state of the economy, and decisions by the central bank, as well as global financial conditions and the risk presented by individual borrowers. No single factor explains every movement.
Are higher interest rates good or bad?
It depends on whether you are borrowing or saving. Higher rates generally mean higher borrowing costs but better returns for savers, while lower rates mean cheaper borrowing but lower returns on savings. The overall effect on the economy is more complex than either side alone.
Should I choose a fixed or a variable rate?
That depends on how much certainty you need, how much room your budget has for higher payments, and how long you will borrow for. There is no universally right answer, and the choice should be made with current product terms in front of you, and with advice if the sums are large.
Does the interest rate affect the total amount I repay?
Yes, substantially, especially on long-term borrowing such as a mortgage. The rate, the length of the borrowing, and whether interest compounds all affect the total repaid, which is why comparing total cost matters more than comparing headline rates alone.
Conclusion
An interest rate is simply the price of using money, but its effects reach into every corner of household and business finance. It shapes what borrowing costs, what saving earns, what a mortgage payment looks like, and how confidently a business can plan for the future. Understanding what moves rates, how fixed and variable rates differ, and how to compare total costs gives borrowers and savers a far stronger position than reacting to each rate announcement as it comes.
The practical lesson is to plan for movement, not just for the current rate: budget with room for rises, compare total costs rather than headline rates, and review borrowing and savings as circumstances change. This guide is general information only and is not financial advice, and no current rate figures have been stated because rates change frequently; check current rates and terms from lenders, and take professional advice before borrowing, fixing a rate, or making a significant savings decision.